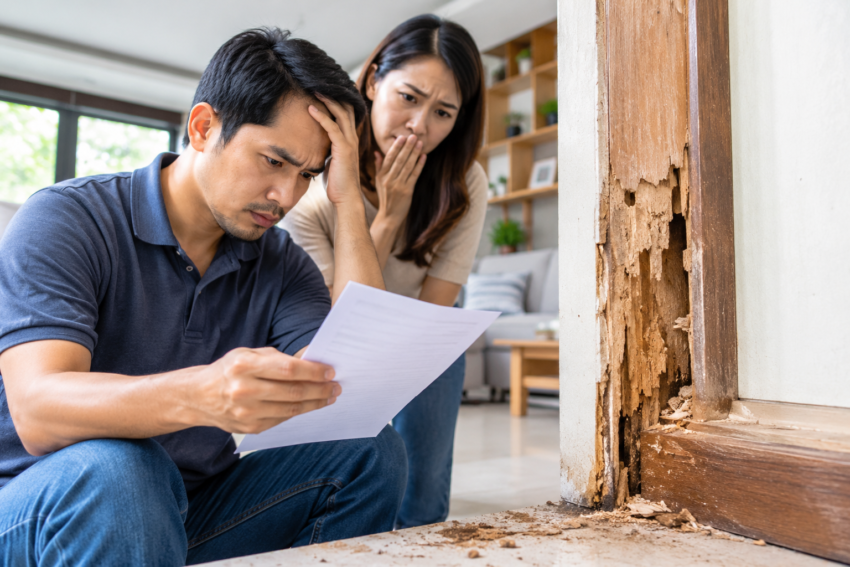
Homeowners may face unexpected financial pressure when damage develops inside their properties, particularly when the cause falls outside the protection provided by standard insurance policies. Termite infestations, gradual deterioration and neglected maintenance can leave property owners responsible for expensive repairs, even when they already have home insurance.
The issue highlights a critical question for consumers: does having home insurance necessarily mean a house is protected against every type of damage?
In many markets, the answer is no.
Standard home insurance policies generally focus on specified risks, such as fire, storms and certain types of accidental damage. However, damage caused by insects, including termites, is commonly excluded because insurers often classify it as a maintenance issue rather than a sudden and unexpected event.
The precise exclusions and exceptions depend on the policy and the applicable insurance regulations.
The Difference Between Insurance and Maintenance
One of the most common misunderstandings among homeowners is the assumption that insurance will pay for any significant damage to a property.
In practice, insurers distinguish between unexpected events and problems that develop gradually over time.
Termites, for example, can damage wooden structures, flooring and other building components before homeowners notice visible signs of an infestation. By the time the problem is discovered, repairs may involve more than replacing a small section of damaged wood.
Because infestations can develop over an extended period, standard policies often exclude both pest treatment and repairs directly attributable to termite activity.
This distinction can become particularly important when homeowners discover damage during renovations or property inspections.
A house may have an active insurance policy but still contain structural problems that are not covered. Understanding this difference before purchasing a policy can help consumers avoid unrealistic expectations about future claims.
Why Policy Wording Matters
Insurance coverage is determined not only by the type of policy purchased but also by its specific terms, exclusions, limits and conditions.
A policy might cover fire damage while excluding the underlying problem that contributed to the incident. Similarly, damage associated with water intrusion, mold, insects or long-term deterioration may receive different treatment depending on the circumstances.
In some cases, an insurer may cover damage resulting from a separate insured event even when the original problem is excluded. However, coverage cannot be assumed simply because two events are connected.
For example, if a homeowner discovers termite damage after a plumbing leak, the existence of the leak does not automatically establish that the resulting damage is insured. The insurer may examine the cause, timeline and applicable policy provisions before making a decision.
Homeowners should therefore review the full policy document rather than relying solely on promotional descriptions of insurance benefits.
Prevention Can Be as Important as Coverage
Although insurance can provide financial protection against covered events, preventive maintenance remains an important part of property ownership.
Homeowners can reduce the likelihood of certain problems by repairing leaking pipes, maintaining gutters, controlling moisture and inspecting vulnerable areas of their properties.
Regular inspections may also help identify early signs of termite activity, including mud tubes, damaged wood and discarded wings near windows or doors.
These measures cannot eliminate every risk, but early detection may limit the extent of damage and reduce repair costs.
Property owners should also keep inspection reports, photographs, maintenance records and repair receipts. Such documentation can help establish the condition of a property and provide useful evidence if an insurance claim becomes necessary.
An Opportunity for Greater Insurance Transparency
The challenges surrounding property insurance also raise broader questions about how insurers communicate exclusions to consumers.
Policy documents can contain technical language that makes it difficult for first-time buyers to distinguish between covered events and excluded losses.
Clearer explanations, practical examples and accessible policy summaries could help consumers make more informed purchasing decisions.
Insurers and insurance intermediaries can also help by explaining common exclusions before customers commit to a policy. Meanwhile, consumers should ask specific questions about structural damage, water-related losses, pest infestations and maintenance requirements.
These discussions are particularly important for buyers of older properties, homes in humid environments and buildings with extensive wooden components.
Making More Informed Insurance Decisions
The value of home insurance depends on how well its coverage matches a property’s risks and the owner’s financial circumstances.
Before purchasing or renewing a policy, homeowners should compare coverage limits, deductibles, exclusions and claim conditions. They should also determine whether additional coverage or a separate service agreement is available for risks that standard insurance does not address.
Most importantly, consumers should avoid assuming that every repair expense will qualify for reimbursement.
A clear understanding of policy limitations, combined with regular property maintenance, can help homeowners manage financial risks more effectively.
As housing costs and repair expenses remain important concerns for households, understanding what insurance does not cover is just as essential as knowing what it does.